You pay your motor insurance. You have life insurance through your employer. So, what is personal accident cover uk? It is the most misunderstood safety net in Britain. Consumers assume life insurance covers everything. It does not. Life insurance pays out if you die. Personal accident cover injects a massive tax-free cash sum into your bank account if you survive a horrific accident but are left with a life-altering injury.
Here is exactly how this policy separates financial survival from absolute ruin when the worst happens on UK roads, at work, or at home.
Decoding What Is Personal Accident Cover UK Actually For
The United Kingdom relies heavily on the National Health Service (NHS). If you are involved in a catastrophic road traffic collision on the M1, the ambulance is free. The emergency trauma surgery is free. The hospital bed is free. Because the immediate medical crisis is handled without an upfront invoice, millions of Britons suffer from a dangerous financial illusion. They believe they are fully protected.
The NHS treats your physical body. They do not pay your mortgage.
If you are discharged from the hospital in a wheelchair, the true financial nightmare begins. You must continue to pay your council tax, fund your weekly groceries, and service your existing debts. More critically, you may need to entirely retrofit your home. Widening doorways, installing a stairlift, and converting a ground-floor room into an accessible wet room can cost tens of thousands of pounds.
Personal Accident (PA) cover exists to bridge this exact gap. It is a specialized indemnity policy that pays a guaranteed, tax-free lump sum of compensation directly to the policyholder following a severe physical trauma. You can use this capital to pay off your mortgage, fund private rehabilitation, adapt your vehicle, or simply survive while you retrain for a completely new, desk-based career.
The Insurance Showdown: PA vs. Life Insurance vs. Income Protection
The biggest myth perpetuated in the UK financial sector is the “overlap myth.” Policyholders frequently cancel their PA cover because they mistakenly believe their newly purchased life insurance renders it redundant.
Insurance underwriters are ruthless with their definitions. Every financial product has a highly specific “trigger event.” If you do not meet the exact definition of that trigger, you receive nothing. To understand the true value of a PA policy, you must see how it contrasts with the other major safety nets.
| Product | The Trigger Event | Payout Type | Main Benefit | Best For |
| Personal Accident (PA) | Surviving an external, sudden, and unforeseen physical trauma. | Immediate, tax-free lump sum (e.g., £100,000). | Fast capital injection to cover extreme life changes or home adaptations. | High-mileage drivers, manual workers, and tradespeople. |
| Life Insurance | The death of the policyholder (or terminal diagnosis with <12 months to live). | Immediate, tax-free lump sum paid to beneficiaries. | Clears the family mortgage and replaces lost future income for dependents. | Anyone with dependents or joint mortgage liabilities. |
| Income Protection | Being medically signed off work due to either accident or illness. | Monthly drip-feed of cash (up to 60-70% of gross salary). | Pays ongoing household bills while you are unable to earn a wage. | Professionals reliant on a monthly salary to survive. |
| Critical Illness Cover | Diagnosis of a specific, listed disease (e.g., cancer, stroke, heart attack). | Immediate, tax-free lump sum. | Financial survival during severe medical treatments. | Broad protection against biological diseases. |
How Payouts Work: The “Scale of Benefits” Matrix
A personal accident policy is not a blank cheque. If you suffer an injury, you cannot simply demand £50,000 for “pain and suffering” like you might in a third-party civil litigation claim.
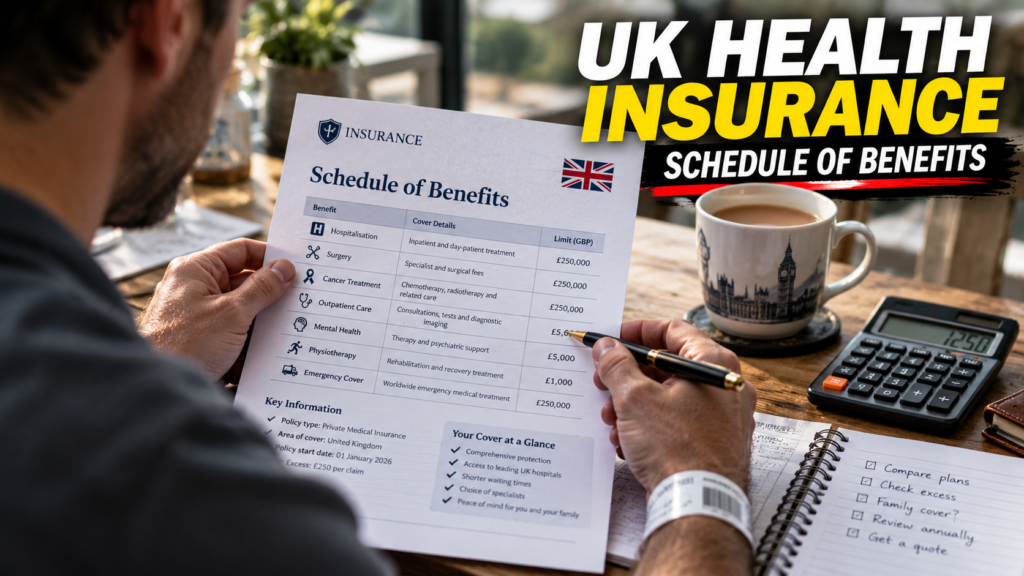
Instead, PA policies operate on a highly rigid, contractual framework known as the Schedule of Benefits (or Scale of Benefits).
When you purchase a policy, you select a “Maximum Capital Sum.” Let us assume you select a £100,000 policy. The underwriter then assigns a strict percentage of that maximum sum to specific anatomical losses. The more catastrophic the loss, the higher the percentage you receive. It is a cold, mathematical calculation based entirely on medical evidence.
| Injury Type (Medical Definition) | Typical Payout Percentage | Payout on a £100,000 Policy |
| Accidental Death | 100% | £100,000 (Paid to estate) |
| Permanent Total Disablement (PTD) | 100% | £100,000 |
| Loss of Two Limbs (above wrist/ankle) | 100% | £100,000 |
| Total & Irreversible Loss of Sight (Both Eyes) | 100% | £100,000 |
| Loss of One Limb or One Eye | 50% | £50,000 |
| Permanent Loss of Speech or Hearing (Both Ears) | 50% to 100% | £50,000 to £100,000 |
| Loss of a Thumb or Index Finger | 15% to 20% | £15,000 to £20,000 |
| Fractured Major Bone (Leg, Arm, Pelvis) | Fixed Sum | £500 to £1,000 |
| Hospital Cash Benefit (Per 24 Hours Admitted) | Fixed Sum | £50 to £100 per night |
This matrix provides absolute certainty. If a surgeon amputates your leg following a motorcycle crash, you do not need to hire a solicitor to argue over the value of your limb. You submit the medical records, and the insurer wires 50% of your capital sum directly into your current account.
The Mechanics of Disablement: PTD vs. TTD
Beyond the physical severance of limbs, the core value of a PA policy lies in its disablement clauses. These are broken down into two strict categories: Permanent Total Disablement (PTD) and Temporary Total Disablement (TTD).
Permanent Total Disablement (PTD)
PTD is the ultimate catastrophic safety net. It triggers a 100% payout of your capital sum if an accident leaves you so severely damaged—such as suffering severe spinal cord trauma or catastrophic brain injury—that a medical professional declares you will never be able to work again.
However, you must read the fine print. Insurers define PTD in one of two ways:
- Any Occupation: This is the cheapest and most restrictive definition. The insurer will only pay out if your injuries are so severe that you cannot perform any job in the UK economy. If you are a scaffolder who breaks their back, you can no longer build scaffolding. But if you can still answer phones in a call centre from a wheelchair, the insurer will deny the PTD claim.
- Own Occupation: This is the premium, highly desirable definition. The policy pays out if you can no longer perform the specific duties of your current job. If a skilled surgeon permanently loses the use of their index finger, they can never operate again. Under an “Own Occupation” clause, they receive the full £100,000 payout, even if they later take a job as a medical university lecturer.
Temporary Total Disablement (TTD)
Not all accidents are permanent. If you break your pelvis, you will eventually heal, but you might be confined to a bed for four months.
Many comprehensive PA policies include a TTD benefit. Rather than a massive lump sum, TTD provides a weekly cash payment (e.g., £250 per week) for a maximum period, usually 52 or 104 weeks. This functions as a short-term income replacement, ensuring you can keep up with the mortgage and utility bills until the plaster casts are removed and you can return to the workforce.
Sickness vs. Accident: The Brutal Underwriting Reality
If you take one piece of broker truth away from this guide, let it be this: An illness is never an accident.
Insurance companies are uncompromising regarding the “proximate cause” of an incident. In UK insurance law, an accident must be a “sudden, unforeseen, and identifiable external event.” If the root cause of your injury stems from biology, genetics, or disease, your Personal Accident claim will be aggressively denied.
Consider this devastating, yet common, scenario:
You are driving down a quiet country lane. Suddenly, you suffer a massive myocardial infarction (a heart attack). The pain causes you to lose consciousness at the wheel. Your vehicle veers off the tarmac and strikes a solid oak tree at 50mph. You survive, but the violent impact crushes your legs, requiring a double amputation.
You submit a claim for the loss of two limbs to your PA insurer. They reject it.
Why? Because the proximate cause of the crash was the heart attack—an internal medical illness. Had a deer run into the road causing you to swerve into the tree, the claim would be paid immediately, because the deer is a sudden, external event.
This is why PA cover must never replace Critical Illness cover. They are two halves of the same shield. One protects you from the environment; the other protects you from your own biology.
Car Insurance Add-Ons vs. Standalone Policies
If you drive a car in the UK, you have likely encountered PA cover without realizing it. When you renew your comprehensive motor insurance on a price comparison website, you are usually prompted to add “Personal Injury Cover” for an extra £15 or £20 a year.
The vast majority of motorists click “Yes,” assuming this £20 add-on fully protects them in a major crash. It does not.
The PA cover bolted onto standard UK car insurance is notoriously weak. It is usually capped at a pathetic maximum payout of £5,000.
If you are involved in a high-speed collision and suffer permanent paralysis, £5,000 is an insult. It is a drop in the ocean compared to the lifetime financial losses you are about to endure. It will not even cover the cost of a high-end customized wheelchair, let alone replace a decade of lost salary. Furthermore, motor add-ons usually only apply if you are injured in the insured vehicle.
A Standalone Personal Accident Policy is entirely detached from your vehicle. It covers you 24 hours a day, 365 days a year. Whether you are hit by a car while crossing the street as a pedestrian, fall off a ladder while cleaning your gutters, or suffer a severe burn while cooking, a standalone policy triggers. More importantly, standalone policies offer capital sums that actually alter your financial reality—ranging from £50,000 up to £500,000.
If you are a primary breadwinner, relying on a £5,000 car insurance add-on to protect your family’s future is a severe miscalculation.
Navigating The Fine Print Exclusions
No insurance policy pays out unconditionally. The Financial Conduct Authority (FCA) requires underwriters to explicitly list what is excluded from the cover. To avoid paying premiums for a useless policy, you must understand the standard UK exclusions.
If you trigger any of the following clauses, your claim will be instantly dismissed:
- Intoxication (Alcohol and Drugs): If a toxicology report proves you were under the influence of illegal narcotics, or operating a vehicle above the legal alcohol limit when the accident occurred, the policy is voided. Insurers will not subsidize illegal or deeply reckless behavior.
- Self-Inflicted Injuries: Any injury deemed by a medical professional or coroner to be deliberate or self-inflicted will not result in a payout. Accidental death benefits are strictly withheld in the event of suicide.
- Hazardous Pursuits & Extreme Sports: Standard policies are priced based on the daily risks of an average commuter or office worker. If you break your neck off-piste skiing in the Alps, amateur motor racing at Silverstone, or participating in a mixed martial arts tournament, you will not be covered. If you engage in extreme hobbies, you must declare them to the broker and pay an additional “hazardous pursuits” premium.
- Acts of Terrorism and War: Most civilian PA policies contain blanket exclusions for injuries sustained during acts of war, civil riots, or international terrorism.
- Pre-Existing Physical Defects: If you have a severe, pre-existing joint condition, and a minor slip exacerbates it, the insurer may argue that the accident was not the sole cause of the disablement, reducing or denying the payout.
A Step-by-Step Guide to Reading Your Policy Document
Do not wait until you are sitting in a hospital waiting room to discover what your policy actually covers. Use this actionable workflow to audit your financial safety net tonight.
Step 1: Locate the Schedule of Benefits
Open your policy booklet and find the grid detailing the exact percentages paid out for specific injuries. Ensure that the “Maximum Capital Sum” is actually high enough to clear your outstanding debts.
Step 2: Check the PTD Definition
Search the document for “Permanent Total Disablement.” Read the legal definition. Does it say “Own Occupation” or “Any Occupation”? If it says “Any Occupation,” recognize that it will be incredibly difficult to claim unless the injuries are catastrophically debilitating.
Step 3: Audit Your Motor Add-on
Log into your car insurance portal. Check the “Personal Accident” limit. If it is £5,000 or £10,000, acknowledge that this is merely a token gesture. It is designed to cover immediate funeral expenses or short-term bills, not long-term survival.
Step 4: Exploit the 14-Day Cooling-Off Period
Under UK consumer law, you possess a statutory 14-day cooling-off period after purchasing any financial product. If you buy a policy, read the fine print, and realize your weekend mountain biking hobby is excluded, you can cancel the policy immediately for a full refund without penalty.
FCA Regulations and the Tax-Free Advantage
The UK personal accident insurance market is strictly regulated by the Financial Conduct Authority (FCA). This ensures that underwriters cannot arbitrarily change the scale of benefits after an accident has occurred, and provides consumers with a direct route of appeal to the Financial Ombudsman Service (FOS) if a claim is unfairly rejected.
The greatest structural advantage of this product, however, comes from HM Revenue & Customs (HMRC).
Because you pay the monthly premiums for a personal accident policy out of your own post-tax income (money you have already paid Income Tax and National Insurance on), HMRC generally views the resulting compensation as entirely tax-free.
Whether you receive a £1,000 fixed sum for a broken arm, or a £250,000 lump sum for a Permanent Total Disablement, that money lands in your account without the government taking a single penny. It does not push you into a higher tax bracket, and it is not subject to Capital Gains Tax. You absorb the cost of the premium upfront, and you reap the uncompromised financial benefit precisely when you need it most.
Take control of your financial architecture today. Review your existing life insurance, audit the limits on your car insurance add-ons, and calculate exactly how much capital your family would need to survive if your physical ability to earn a living was stripped away in a fraction of a second.
Pingback: Is Personal Accident Cover Worth It? A Detailed UK Review - Personal Accident UK
Pingback: How to Make a Personal Accident Claim: A Step-by-Step UK Guide - Personal Accident UK
Pingback: What is Personal Accident Cover in Car Insurance? (7 Vital Facts)
Pingback: Personal Accident and Sickness Insurance: The Essential UK Guide 2026
Pingback: Personal Accident Insurance for Horse Riding: The Essential UK Guide
Pingback: How Much Personal Accident Cover Do I Need? The Essential UK 2026 Guide